The Digital Frontier: The Evolutionary Horizon of Sovereign Money
For three millennia, sovereign legal tender has existed as a tangible physical token—whether a cast bronze coin, a stamped silver tetradrachm, or an intaglio-printed cotton banknote. Today, society stands at the precipice of the most profound monetary paradigm shift since the invention of the printing press: the migration toward cashless economies and Central Bank Digital Currencies (CBDCs).
This transition is not merely technological; it represents a fundamental re-engineering of state sovereignty, commercial privacy, monetary velocity, and the constitutional definition of legal tender in an interconnected global digital economy.
🪙
Part I: Cash Velocity
The Accelerating Decline of Physical Cash Velocity
The trajectory of physical currency in daily retail commerce has experienced a steep, irreversible decline across advanced economies over the past two decades. Driven by the ubiquity of smartphone contactless payment systems (such as Apple Pay, Google Wallet, and WeChat Pay), near-field communication (NFC) chip cards, and seamless digital banking apps, consumer payment habits have transformed. In nations like Sweden and Norway, cash transactions now account for less than five to eight percent of all retail point-of-sale payments, with hundreds of bank branches, public buses, and commercial retailers refusing to accept physical banknotes entirely.
This rapid cashless transition was dramatically accelerated by the global COVID-19 pandemic, which catalyzed contactless payment thresholds and online e-commerce infrastructure. However, the private digital payment architecture that replaced physical cash is entirely dependent upon commercial banking intermediaries, payment network processors (such as Visa, Mastercard, and American Express), and private technology corporations. When a consumer swipes a debit card or taps their phone, they are not spending sovereign legal tender; rather, they are transferring private commercial bank credit that requires settlement across clearinghouses, subject to transaction interchange fees, merchant surcharges, and digital network outages.
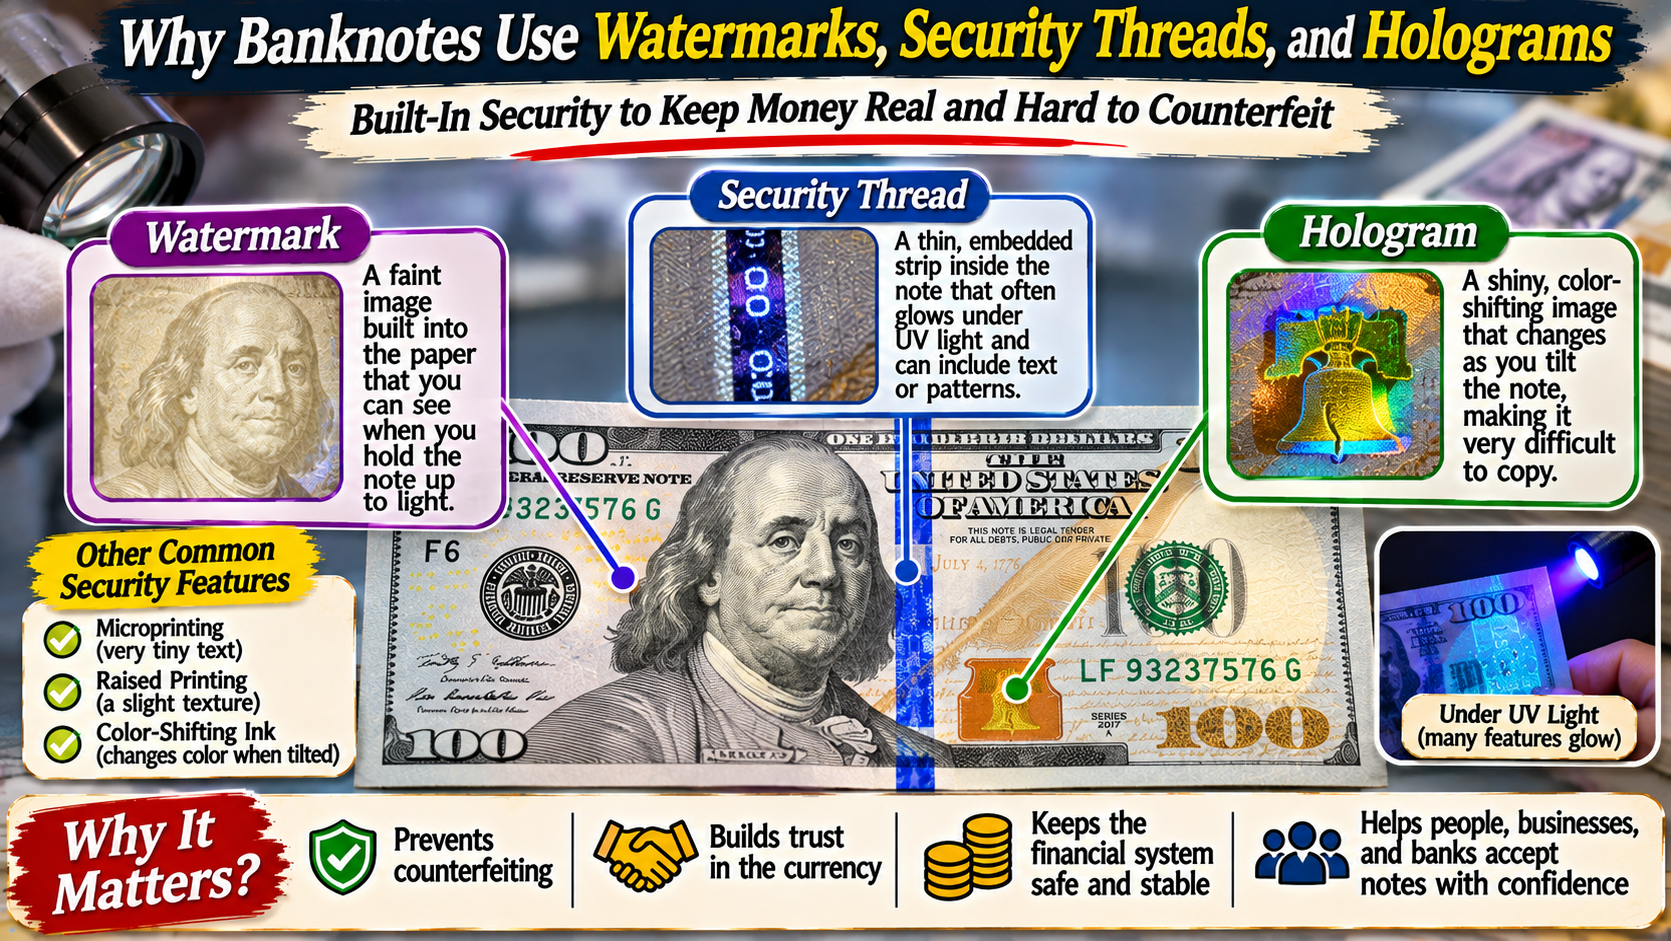
Physical cash possesses three unique, irreplaceable economic and civil liberties attributes that private digital payments lack: absolute privacy (cash leaves no digital tracking footprint, profiling database, or advertising trail), instant universal settlement (the exchange of a banknote settles the debt immediately without counterparty risk), and offline availability (cash functions during electrical grid failures, hurricanes, cyberattacks, and telecommunication blackouts). As physical cash velocity wanes, central banks worldwide are confronted with an existential crisis: if physical banknotes vanish from public circulation, citizens will have no direct access to sovereign state money, forcing entire populations into the monopolistic grip of commercial banking databases.
| Architectural Metric | Physical Banknote Cash | Commercial Bank Digital Money | Retail Central Bank Digital Currency (CBDC) | Wholesale CBDC |
|---|---|---|---|---|
| Issuing Entity | Sovereign Central Bank | Private Commercial Banks | Sovereign Central Bank directly to public | Central Bank to commercial financial institutions |
| Legal Nature | Direct claim on central bank; legal tender | Commercial credit claim; private bank liability | Direct digital liability of central bank; legal tender | Direct digital reserve asset on central bank ledger |
| Transactional Privacy | Absolute anonymity; zero data logging | Fully tracked, monitored by banks, AML/KYC logs | Programmable privacy; tiered verification protocols | Confidential inter-bank regulatory reporting |
| Offline Functionality | 100% functional without electricity/internet | 0% functional during network/power outage | Hardware cryptographic offline storage chips | Requires dedicated high-security server backbone |
| Intermediary Fees | Zero transaction fees for buyers/sellers | 1.5% to 3.5% interchange fees on merchants | Zero or near-zero state-mandated public utility | Wholesale clearing settlement fee optimizations |
| Leading Global Pilots | All sovereign nations (circulating paper/coins) | Global private banking sector | e-CNY (China), Sand Dollar (Bahamas), Digital Euro | Project mBridge (BIS), Project Helvetia (SNB) |
⚖️
Part II: Defining CBDCs
What Is a CBDC? Defining Sovereign Digital Legal Tender
To navigate the ongoing monetary revolution, one must rigorously define what a Central Bank Digital Currency is—and what it is not. A CBDC is not a volatile, speculative cryptocurrency like Bitcoin or Ethereum; it is not backed by decentralized algorithmic mining, nor does its purchasing power fluctuate against national accounting units. A CBDC is simply a digital form of a country’s sovereign currency, denominated in the national unit of account (such as the US dollar, euro, or Japanese yen) and issued as a direct liability of the central bank rather than a commercial bank.
Economists divide CBDCs into two distinct operational models: Wholesale CBDCs and Retail (General Purpose) CBDCs. Wholesale CBDCs are designed exclusively for financial institutions, commercial banks, and central banks to settle large-scale interbank payments, cross-border foreign exchange transactions, and securities trading with instant atomic settlement, eliminating days of clearing latency and multi-currency correspondent banking fees. Initiatives such as Project mBridge (developed by the Bank for International Settlements Innovation Hub alongside the central banks of China, Hong Kong, Thailand, and the UAE) demonstrate that wholesale CBDCs can execute international settlements in seconds at a fraction of standard SWIFT network costs.
In contrast, Retail CBDCs are designed for the general public, functioning as a digital complement to physical banknotes. Under a two-tier retail CBDC architecture—favored by the European Central Bank and the Bank of England—the central bank issues the digital currency and maintains the secure master ledger, while licensed commercial banks and authorized fintech payment providers distribute the CBDC through digital mobile wallets, manage customer interfaces, and perform anti-money laundering (AML) and know-your-customer (KYC) identity checks.
🏛️
Part III: Global Pilots
The Frontrunners: The Sand Dollar, China’s e-CNY, and the Digital Euro
While theoretical debates occupy western policy institutes, several nations have already launched functional, full-scale retail CBDCs. In October 2020, the Central Bank of The Bahamas made history by deploying the world’s first nationwide retail CBDC: the Sand Dollar. The Bahamas was uniquely motivated by geography: a sprawling archipelago of over seven hundred islands and cays, commercial banks frequently closed unprofitable brick-and-mortar branches on remote outer islands, leaving rural islanders without banking services. Furthermore, devastating hurricanes regularly crippled electrical grids and washed away physical cash reserves. The Sand Dollar enabled all Bahamian citizens to conduct digital payments via mobile wallets, even with intermittent telecommunication connections.
The most colossal and technologically sophisticated CBDC deployment in the world is China’s digital yuan, officially termed the e-CNY (Electronic Chinese Yuan) or Digital Currency Electronic Payment (DCEP). Administered by the People’s Bank of China (PBOC), the e-CNY pilot has expanded to encompass hundreds of millions of users and billions of dollars in cumulative transaction volume across major metropolitan hubs, including Shanghai, Beijing, and Shenzhen. The e-CNY is integrated into public transportation turnstiles, utility bill portals, e-commerce giants, and specialized physical smart cards equipped with e-ink displays showing account balances, enabling elderly citizens to tap-to-pay without smartphones.
In the West, the European Central Bank launched its formal ‘Preparation Phase’ for the Digital Euro in November 2023. Envisioned as an electronic banknote for the digital age, the Digital Euro is being engineered to guarantee that citizens across the twenty Eurozone nations always have access to a completely free, universally accepted, privacy-compliant public digital payment solution, preventing European payment infrastructure from being completely dominated by foreign non-European duopolies.
👑
Part IV: Civil Liberties Dilemmas
The Critical Constitutional Dilemmas: Privacy, Disintermediation, and Control
Despite their undeniable technological efficiencies, Central Bank Digital Currencies have sparked intense democratic debate regarding civil liberties, surveillance, and constitutional rights. The paramount concern centers upon consumer financial privacy. Unlike physical banknotes—which can be exchanged between two individuals with total anonymity—a digital ledger records every transaction timestamp, merchant identity, location, and monetary amount. Critics warn that in the hands of authoritarian regimes, a fully centralized CBDC could become the ultimate surveillance weapon, enabling governments to track political dissidents, freeze funds without due process, or enforce programmable expiration dates that compel citizens to spend money before a set deadline.
To mitigate these fears, democratic central banks emphasize ‘privacy by design’. The European Central Bank has proposed strict privacy protocols where low-value, offline digital euro transactions between individuals would involve zero data sharing with the central bank or commercial intermediaries, replicating the anonymity of physical cash. Furthermore, central banks emphasize that CBDCs must not possess ‘programmable money’ capabilities that restrict what goods citizens can purchase, maintaining the fungibility of sovereign tender.
A second profound economic threat is commercial bank disintermediation. In the traditional financial system, commercial banks rely on citizen deposits to fund mortgage loans, small business credit, and economic investment. If citizens suddenly perceive a retail CBDC—which is a risk-free direct liability of the central bank—as safer than a private commercial bank deposit during a financial panic, a catastrophic ‘digital bank run’ could occur in seconds. Citizens could transfer their commercial bank savings into the CBDC with the tap of a smartphone button, collapsing the commercial banking sector. To prevent this, central banks are implementing strict individual holding limits (such as a proposed cap of €3,000 per citizen in the Digital Euro) and zero interest rate policies on consumer holdings.
📜
Part V: The Permanent Role of Cash
The Resilient Horizon: Why Physical Cash Will Never Entirely Disappear
As the digital frontier advances, central bankers and monetary historians have reached a crucial consensus: Central Bank Digital Currencies are designed to coexist with, rather than eliminate, physical cash. Multiple nations that aggressively pursued cashless policies have enacted legislation legally mandating that all commercial retailers, pharmacies, and grocery stores accept physical banknotes and coins under penalty of fines. Lawmakers recognize that millions of marginalized citizens—including the unbanked, elderly populations, low-income communities, and children—rely exclusively on physical money to survive.
Furthermore, national security strategists view physical banknotes as a vital civil defense infrastructure. In a geopolitical environment characterized by state-sponsored cyber warfare, satellite disruptions, subsea fiber-optic cable sabotage, and catastrophic climate-driven power outages, a society that relies 100 percent on digital payments is exposed to catastrophic systemic collapse. The physical banknote—compact, indestructible, untrackable, and requiring zero electricity—remains the ultimate sovereign failsafe of human civilization.
The future of monetary history will not be a monolithic digital monoculture, but a dynamic, resilient hybrid ecosystem. Physical cash will endure as the tangible, anonymous anchor of personal liberty and crisis resilience, while central bank digital currencies provide the high-velocity, frictionless infrastructure for global digital commerce. Together, they represent the continuing evolution of a sacred social contract that began thousands of years ago in Lydia and ancient China: the sovereign promise that money is the trusted measure of human labor and exchange.
Key Takeaways: Cashless Trends and CBDCs
Decline of Cash Velocity: Contactless phone and card payments have reduced cash retail use to under 10% in northern Europe, driving central banks toward digital sovereign tender.
What CBDCs Are: A direct digital liability of the central bank rather than commercial bank credit, maintaining the sovereign legal tender status of national money.
Global Deployment: The Bahamas Sand Dollar and China’s e-CNY lead real-world deployment, with Europe actively developing the privacy-focused Digital Euro.
The Enduring Role of Cash: Physical cash remains constitutionally protected as a critical civil liberties safeguard, crisis-proof failsafe, and barrier against digital surveillance.
Cryptographic Offline Hardware Tokens and Civil Emergency Resilience
A paramount technical barrier to universal CBDC adoption is solving the ‘consecutive offline payment problem’. In standard digital payment architectures, every financial transaction requires an immediate internet handshake with a centralized cloud database to verify that the payor actually possesses the funds and to prevent ‘double-spending’ (the digital fraud of duplicating digital data to spend the exact same unit of money twice). However, in rural communities without cellular coverage, during major natural catastrophes (such as hurricanes, earthquakes, and floods), or amid intentional hostile EMP (electromagnetic pulse) attacks, cellular towers and fiber-optic networks fail entirely.
To overcome this vulnerability, central bank cryptographic engineers are partnering with leading semiconductor foundries to develop dual-offline hardware security tokens. Embedded inside specialized smart cards, wearable biometric rings, or secure mobile phone enclaves, these tamper-resistant hardware chips utilize advanced zero-knowledge proofs and localized asymmetric public-key cryptography. When two individuals tap their cards or phones together in an area with zero electrical power or internet access, the secure elements cryptographically decrement the balance on the payor’s hardware chip and increment the balance on the payee’s chip, generating a cryptographically signed cryptographic receipt that reconciles with the central bank ledger once connectivity is eventually restored.
Ultimately, the evolution toward central bank digital currencies highlights the timeless paradox of monetary science. Every technological leap—from ancient Lydian electrum lumps to Roman silver denarii, paper greenbacks, and encrypted cryptographic tokens—strives to balance three competing forces: transactional velocity, counterparty trust, and human liberty. As global society navigates this profound transformation, preserving the anonymity, accessibility, and sovereign dignity of common exchange will remain the definitive challenge of the twenty-first century.